THE VISITOR-TO-INVESTOR ECONOMY — by OUISTARS Travel Intelligence
By Osama Samaha, Editor-in-Chief · Verified 6 September 2026
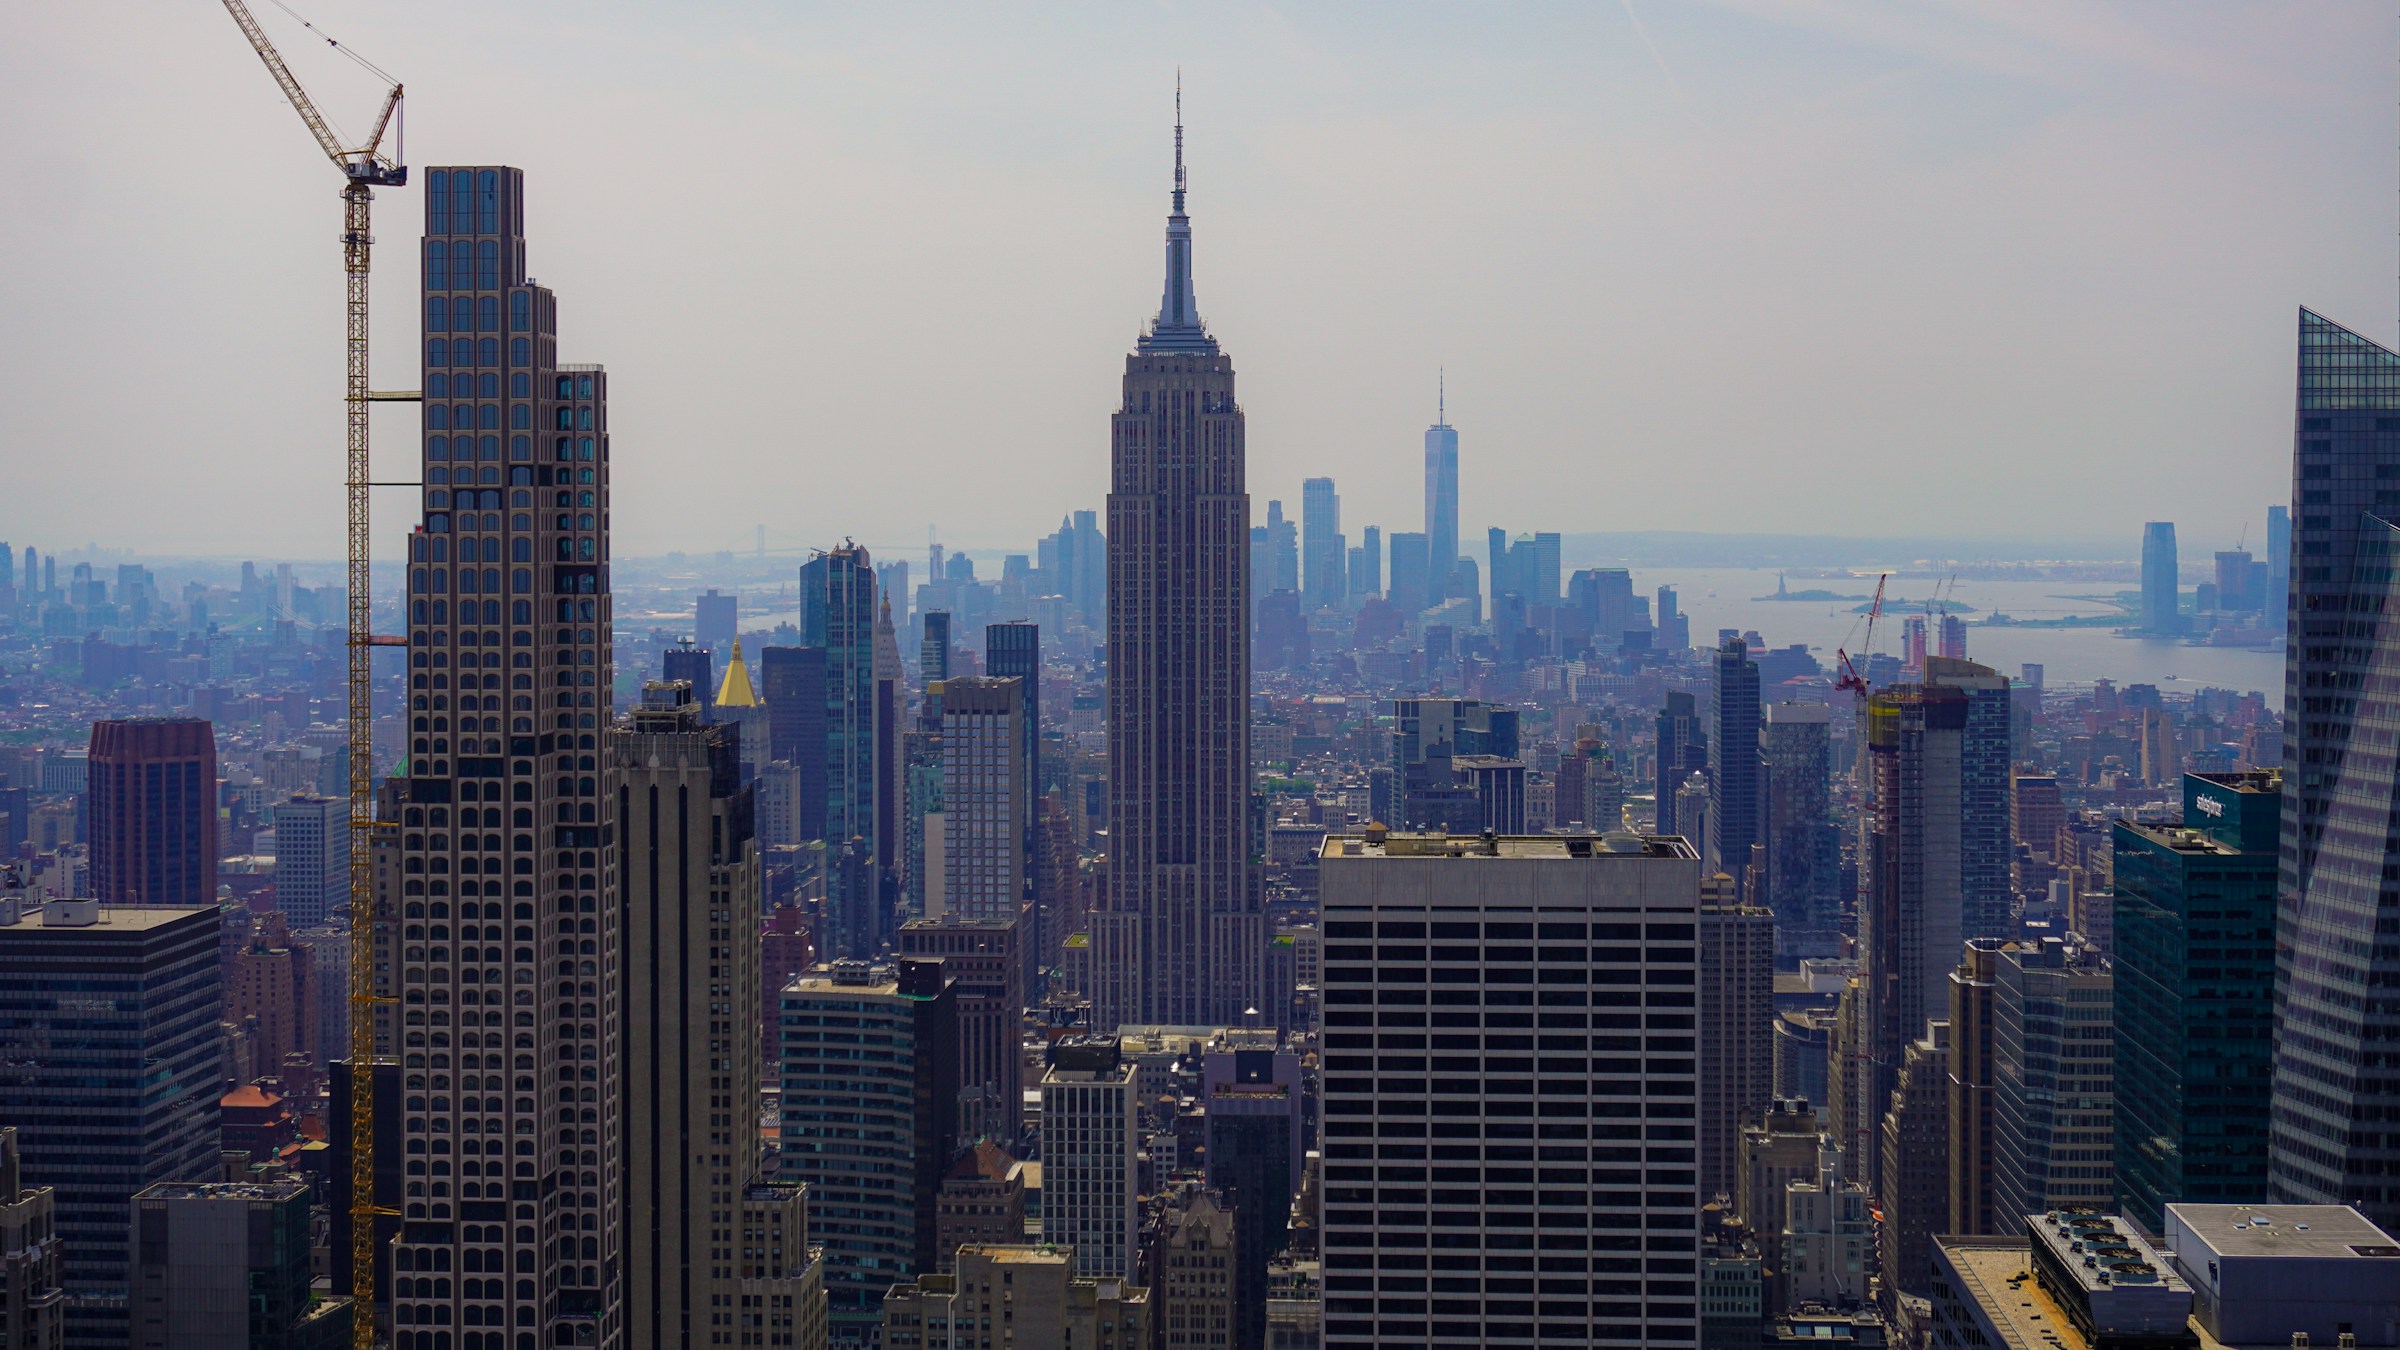
The United States lets many foreigners own homes and companies, but ownership and immigration are separate legal systems. A deed or LLC certificate is not a visa.
Property access is broad, not uniform
There is no single federal ban on ordinary foreign residential ownership. State law governs title, transfer, landlord rules and taxes, and some states restrict particular foreign buyers or land classes. Foreign holdings of agricultural land trigger federal AFIDA reporting. CFIUS can review certain real-estate transactions near sensitive sites. The buyer must therefore check the state, asset type and location—not rely on a national slogan.
Business formation versus status
Foreigners can generally form state-law entities, with registered-agent, tax-ID, licence and beneficial-ownership obligations determined by federal and state rules. That does not authorise work or residence. E-2 is available only to nationals of treaty countries who place substantial, at-risk capital in a real, operating US enterprise and intend to depart when status ends; “substantial” has no universal dollar figure. EB-5 is an immigrant route: generally $1.05 million, or $800,000 in a targeted employment area or infrastructure project, plus creation of at least ten qualifying jobs and full source-of-funds review. Passive home ownership qualifies for neither.
Protection, tax and capital
Recorded deeds, title insurance, escrow, licensed brokers and courts can protect buyers, but the rules and closing practice vary by state. FIRPTA generally requires 15% withholding on the amount realised when a foreign person sells US real property; the withholding is not necessarily the final tax. Rental income is generally taxed at 30% gross unless effectively connected treatment is elected or a treaty changes the result. Property, income, estate and local taxes require cross-border planning.
The US has no general promise that every bank transfer will proceed: AML, sanctions, tax reporting and source-of-funds checks apply. SelectUSA describes an open investment environment, while sector reviews and state regulation preserve real complexity.
Tourism and long stay
The National Travel and Tourism Office recorded about 68.3 million international arrivals in 2025 and forecast about 70.5 million for 2026. Scale, diversity and market depth are advantages. Disadvantages include multi-level regulation, litigation and insurance costs, tax complexity and the sharp separation between ownership and lawful stay.
| Question | Answer |
|---|---|
| Foreign property? | Broadly possible, but state, agricultural and security rules matter. |
| Property residence? | No. |
| E-2? | Treaty nationality plus substantial at-risk operating investment. |
| EB-5? | Qualifying capital and job creation, with immigration adjudication. |
| Main friction? | Federal/state/local complexity and tax compliance. |
Primary sources
- US State Department — E-2 treaty investor visa
- USCIS — EB-5 programme
- IRS Publication 515 — non-resident real-estate tax
- IRS — FIRPTA withholding
- USDA — foreign agricultural land disclosure
- SelectUSA — Investor Guide
- SBA — register a business
- National Travel and Tourism Office — forecasts
Independent editorial analysis; not legal, tax, immigration or investment advice.